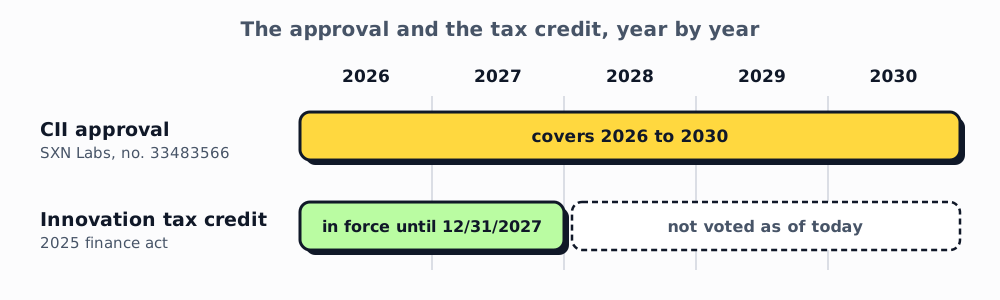
On October 15, the national expertise unit for the innovation tax credit at the DRIEETS Île-de-France, the regional labor and economy administration, granted SXN Labs CII approval no. 33483566, covering the years 2026 to 2030. The application went in on September 1. A French SME that hires me to design software that qualifies as a new product can now include the eligible share of my invoices in its tax credit.
The innovation tax credit
The CII (crédit d’impôt innovation) is limited to SMEs as the EU defines them: fewer than 250 employees, and either revenue under €50 million or a balance sheet under €43 million. It covers the design of prototypes or pilot installations of new products, meaning products not yet on the market that outperform existing ones on technical performance, features, ergonomics or eco-design. Intangible products count, software or a SaaS platform for instance. The production phase is not covered.
In metropolitan France, the rate has been 20% since the 2025 finance act, which cut it from 30%. Eligible expenses are capped at €400,000 a year, so the credit tops out at €80,000. The details are on Entreprendre.Service-Public and entreprises.gouv.fr, both in French.
What the approval is for
An SME that outsources the design of its prototype can only include that spending in its CII if the provider is approved. The approval certifies that the provider has the people and the technical means to carry out this work on behalf of a client.
What the approval does not guarantee
The DRIEETS email that came with the decision points out that the approval does not prejudge whether a given piece of work is eligible. Software that does what products already on the market do is not a new product for tax purposes, and a standard management tool does not become one because it was custom-built. Eligibility is checked project by project, during scoping.
The same email recommends identifying eligible expenses on invoices. SXN Labs invoices will show that share, and the approval decision is available on request for the client’s records.
The CII after 2027
The 2025 finance act extended the CII until December 31, 2027, and the 2026 finance act left it unchanged. The approval runs until 2030, but for expenses incurred from 2028 to 2030 it will only matter if the scheme is extended again.
If you run an SME and the software you have in mind could be a new product, we can look together at what falls under the CII. The FAQ covers the essentials.